It’s not just about having good credit. Here’s the number that gets you in the door and the one that gets you the best rate.
What is a Credit Score?
A credit score is a number (usually between 300-850) that represents your creditworthiness: how likely you are to pay your bills (mortgage, car loan, etc.) on time. A higher score is better.
Your credit score is based on your credit report, which tracks your various credit accounts, the age of those accounts, your payment history, and your credit utilization.
FICO Score
Very Poor: 300-579
Fair: 580-669
Good: 670-739
Very Good: 740-799
Exceptional: 800-850
How Does My Credit Score Affect my Ability to Get Approved for a Mortgage?
Most conventional loans want to see at least a 620. But the score that gets you approved and the score that gets you a good rate are different things.
- 300–619 — Limited options. You may still qualify for FHA or USDA loans, but expect higher rates.
- 620–699 — You’re in the door. Rates will be higher than average but manageable.
- 700–759 — Solid. You’ll qualify for competitive rates with most lenders.
- 760–850 — This is where the best rates live. Even a small improvement in your score at this level can save thousands over the life of your loan.
What Actually Affects Your Score?
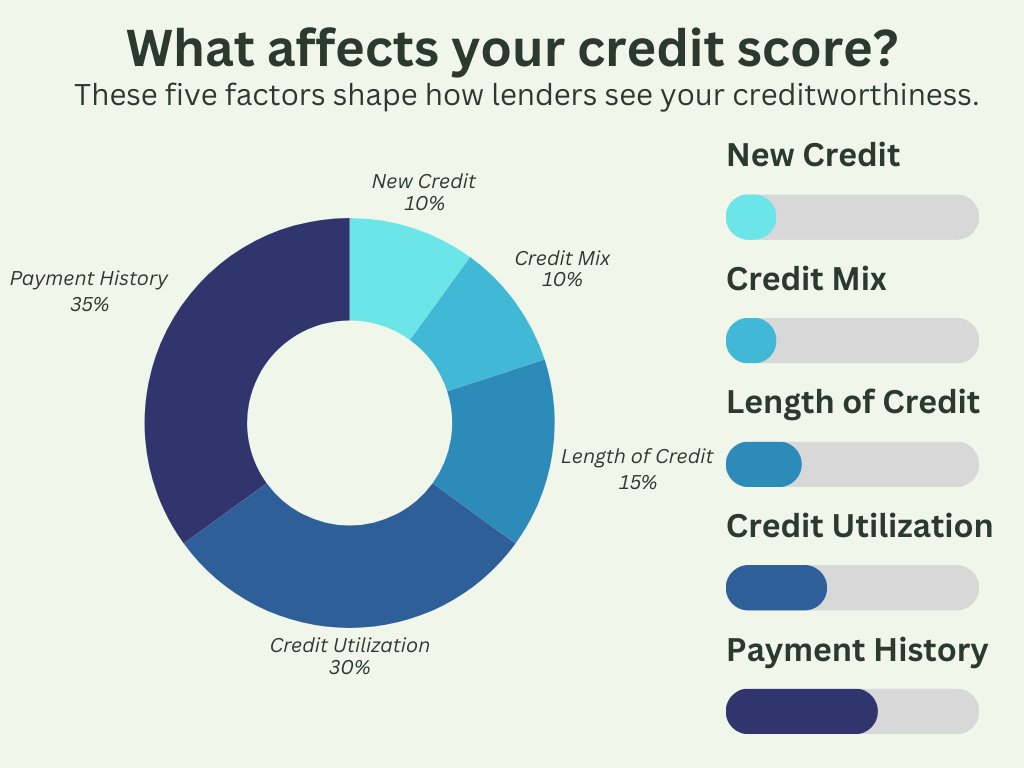
Five factors, in order of importance:
- Payment history (35%) — Do you pay on time? This is the single biggest factor. One missed payment can do real damage.
- Credit utilization (30%) — How much of your available credit are you using? Keep it under 10% if you can, 30% at most.
- Length of credit history (15%) — Older accounts help. This is why you should keep old cards open even if you don’t use them.
- Credit mix (10%) — Having different types of credit — cards, car loans, student loans — works in your favor.
- New credit (10%) — Applying for several new accounts in a short window can temporarily lower your score.
How to Improve Your Score
Most of this comes down to two things: time and consistency.
- Pay everything on time, every time. Set up autopay. A single missed payment hurts more than a dozen on-time payments help.
- Keep card balances low. Aim for under 10% of your credit limit. Carrying a balance doesn’t help your score — it just costs you interest.
- Don’t close old accounts. Even cards you never use contribute to your history and lower your utilization.
- Start early. A strong credit score takes years to build. The sooner you start, the better.
Key Takeaway
Key Takeaway Your credit score is one of the few things standing between you and a good mortgage rate — and it’s entirely within your control.
Things That Might Surprise You
- Having no debt doesn’t mean a good score. Lenders want to see a history of paying debts on time. No debt means no track record.
- Paying off a loan early can temporarily lower your score. Closing an account removes its payment history and reduces your credit mix.
- Applying for a new credit card can actually help. It adds an account, lowers your utilization, and improves your mix — as long as you don’t do it right before applying for a mortgage.
- Your income doesn’t affect your score. A high earner who misses payments has a worse score than a modest earner who never does.
- Rent payments don’t count. Even years of on-time rent payments aren’t factored in. It’s one of the more frustrating quirks of the system.